Here's the latest from MAAR
Low mortgage rates, high affordability and government programs designed to encourage home purchases are continuing to spur home sales this spring despite an iffy economy. The week ending April 18 was the fourth consecutive week of pending sales activity that was more than 20 percent higher than during the same week in 2008. There were 1,083 pending sales for the week, up 21.3 percent from this time last year. It was also the third consecutive week of 1,000-plus unit sales, a first-time occurrence since 2006.
All these sales are quickly whisking inventory off the market at a time when new listing inventory is not growing at its typically robust spring rate. The number of total homes for sale is down 18.4 percent from a year ago at 26,318. As a result, the gap between this year's supply of homes and that of previous years continues to grow.
More HERE.
Tuesday, April 28, 2009


Friday, October 10, 2008
Pending sales skyrocket over 40 percent as prices decline
From MAAR:
Minneapolis, Minnesota (October 10, 2008) – Buyers flocked to the Twin Cities housing market in September to take advantage of attractive home prices and a sunsetting federal loan program, according to the Minneapolis Area Association of REALTORS® (MAAR) based on data from the Regional Multiple Listing Service of Minnesota, Inc.
There were 4,036 pending sales in September, which represented a whopping 42.2 percent increase over September 2007's mark of 2,839. Closed sales, too, were up dramatically—34.9 percent higher for the same time period comparison. The last time there was a year-over-year pending sales increase even close to this large was in March of 1998 when the increase over March of 1997 was 38.6 percent.
"There really are some incredible buying opportunities out there and this is the surest sign yet," said Kevin Knudsen, MAAR President. "But we also need to keep in mind that September of last year was extremely slow, which makes these figures pop a little more."
Also adding to the influx of September buyers was "last call" activity before the October 1 dissolution of the FHA-sponsored seller-funded downpayment assistance program, which was the last of a dying breed of zero-down loan programs remaining on the market.
A hearty 41.6 percent of September's pending sales were lender-mediated foreclosures and short sales, up from 17.5 percent in September 2007. The increased market share of these bargain-priced properties led to further declines in home prices. The overall September median sales price of $189,900 fell from last year by 15.6 percent. Lender-mediated homes posted a median sales price of $146,000, a decrease of 11.5 percent from last year. Traditional properties had a September median sales price of $212,500, a decrease of 8.6 percent.
Due to the decline in home prices and another downtick in mortgage rates, the October Housing Affordability Index jettisoned upward from last month to 159, which is 21.4 percent higher than this time last year, and back up at extremely healthy levels following a few years of unsustainably low affordability. While challenging for sellers, this means a more accessible market for potential home buyers, thus the resurgence in sales activity.
"With all the uncertainties in the economy, it's hard to predict right now if the sales upturn will continue," said Steve Havig, MAAR President-Elect. "But the affordability and inventory choice picture is still very attractive, which bodes well for our long-term picture."
Minneapolis, Minnesota (October 10, 2008) – Buyers flocked to the Twin Cities housing market in September to take advantage of attractive home prices and a sunsetting federal loan program, according to the Minneapolis Area Association of REALTORS® (MAAR) based on data from the Regional Multiple Listing Service of Minnesota, Inc.
There were 4,036 pending sales in September, which represented a whopping 42.2 percent increase over September 2007's mark of 2,839. Closed sales, too, were up dramatically—34.9 percent higher for the same time period comparison. The last time there was a year-over-year pending sales increase even close to this large was in March of 1998 when the increase over March of 1997 was 38.6 percent.
"There really are some incredible buying opportunities out there and this is the surest sign yet," said Kevin Knudsen, MAAR President. "But we also need to keep in mind that September of last year was extremely slow, which makes these figures pop a little more."
Also adding to the influx of September buyers was "last call" activity before the October 1 dissolution of the FHA-sponsored seller-funded downpayment assistance program, which was the last of a dying breed of zero-down loan programs remaining on the market.
A hearty 41.6 percent of September's pending sales were lender-mediated foreclosures and short sales, up from 17.5 percent in September 2007. The increased market share of these bargain-priced properties led to further declines in home prices. The overall September median sales price of $189,900 fell from last year by 15.6 percent. Lender-mediated homes posted a median sales price of $146,000, a decrease of 11.5 percent from last year. Traditional properties had a September median sales price of $212,500, a decrease of 8.6 percent.
Due to the decline in home prices and another downtick in mortgage rates, the October Housing Affordability Index jettisoned upward from last month to 159, which is 21.4 percent higher than this time last year, and back up at extremely healthy levels following a few years of unsustainably low affordability. While challenging for sellers, this means a more accessible market for potential home buyers, thus the resurgence in sales activity.
"With all the uncertainties in the economy, it's hard to predict right now if the sales upturn will continue," said Steve Havig, MAAR President-Elect. "But the affordability and inventory choice picture is still very attractive, which bodes well for our long-term picture."
Monday, October 06, 2008
Party Time Continues!
Here's the latest from MAAR:
The September sales party continued for the week ending September 27, as pending sales jumped by a whopping 58.4 percent from 2007. The extravagant nature of these sales increases will not likely continue through the fall, given the current economic uncertainties and an expected downward trend in consumer confidence. New listings also increased for the same time period, bumping up 9.9 percent from the same week last year—the first year-over-year increase in new listings since early July. Total inventory remains significantly down; there are roughly 3,000 fewer homes for sale now than at this time in 2007.
This week's edition of the MAAR Weekly Market Activity Report features updated figures for several important metrics. The Supply-Demand Ratio (SDR)—a measurement of the number of homes for sale for each projected buyer—stood at 9.79 for October, down slightly from last October. The Percent of Original List Price Received at Sale dipped slightly to 92.2 percent in September, while the Average Days on Market Until Sale increased to 145, up 2.7 percent from last September.
The September sales party continued for the week ending September 27, as pending sales jumped by a whopping 58.4 percent from 2007. The extravagant nature of these sales increases will not likely continue through the fall, given the current economic uncertainties and an expected downward trend in consumer confidence. New listings also increased for the same time period, bumping up 9.9 percent from the same week last year—the first year-over-year increase in new listings since early July. Total inventory remains significantly down; there are roughly 3,000 fewer homes for sale now than at this time in 2007.
This week's edition of the MAAR Weekly Market Activity Report features updated figures for several important metrics. The Supply-Demand Ratio (SDR)—a measurement of the number of homes for sale for each projected buyer—stood at 9.79 for October, down slightly from last October. The Percent of Original List Price Received at Sale dipped slightly to 92.2 percent in September, while the Average Days on Market Until Sale increased to 145, up 2.7 percent from last September.
Wednesday, October 01, 2008
September Song
Her's the latest from MAAR:
September home sales in the Twin Cities housing market continue to post huge gains over 2007. For the week ending September 20, there were 42.8 percent more pending sales than the same week last year. Over the last seven weeks, there have been 5,866 signed purchase agreements, up more than 1,500 units from the 4,363 posted during this period in 2007. However, here are some items to keep in mind that temper the good news:
September 2007 was a particularly slow month, which inflates the appearance of this year's increase. Current sales levels are on par with September 2006.
Lender-mediated foreclosures and short sales are a growing part of the market. For the most recent week, 39.1 percent of pending sales were lender-mediated, compared to 13.4 percent for the same week last year.
Home sales in September of this year may be temporarily propped up by buyers taking advantage of the final days of the FHA seller-funded downpayment assistance program, which disappears on October 1.
The supply of homes for sale remains lower than last year—7.8 percent down from the same time last year for the most recent reporting week.
September home sales in the Twin Cities housing market continue to post huge gains over 2007. For the week ending September 20, there were 42.8 percent more pending sales than the same week last year. Over the last seven weeks, there have been 5,866 signed purchase agreements, up more than 1,500 units from the 4,363 posted during this period in 2007. However, here are some items to keep in mind that temper the good news:
September 2007 was a particularly slow month, which inflates the appearance of this year's increase. Current sales levels are on par with September 2006.
Lender-mediated foreclosures and short sales are a growing part of the market. For the most recent week, 39.1 percent of pending sales were lender-mediated, compared to 13.4 percent for the same week last year.
Home sales in September of this year may be temporarily propped up by buyers taking advantage of the final days of the FHA seller-funded downpayment assistance program, which disappears on October 1.
The supply of homes for sale remains lower than last year—7.8 percent down from the same time last year for the most recent reporting week.
Saturday, September 27, 2008
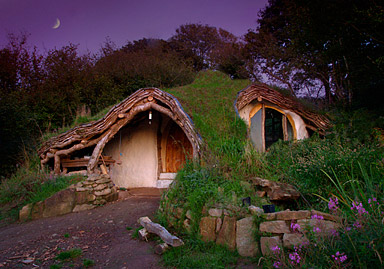
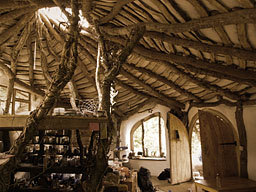
FOR SALE- ONE OWNER HOBBIT HOME
Tired of the Rat Race? Why not try digging your own hole like this guy did in Wales!
Click here for more!
Monday, September 22, 2008
A Nice Little Streak
Here's the latest from MAAR:
As we enter the fall season, buyer activity is still on a nice little streak, posting its sixth consecutive week of double-digit year-over-year growth in pending sales. During this six-week period, there have been 5,085 purchase agreements signed in the Twin Cities housing market compared to only 3,816 during this time in 2007. For the week ending September 13, there were 783 purchase agreements signed—a jump of 23.3 percent over the same time last year.
For that same week there were 1,864 new listings—a decline of 13.4 percent from the same week last year. The total number of homes currently for sale is 31,426, which is down 9.3 percent from this time in 2007. As it does every fall, total supply should continue to decline in the months ahead.
As we enter the fall season, buyer activity is still on a nice little streak, posting its sixth consecutive week of double-digit year-over-year growth in pending sales. During this six-week period, there have been 5,085 purchase agreements signed in the Twin Cities housing market compared to only 3,816 during this time in 2007. For the week ending September 13, there were 783 purchase agreements signed—a jump of 23.3 percent over the same time last year.
For that same week there were 1,864 new listings—a decline of 13.4 percent from the same week last year. The total number of homes currently for sale is 31,426, which is down 9.3 percent from this time in 2007. As it does every fall, total supply should continue to decline in the months ahead.
Tuesday, September 16, 2008
Who says all sequels are bad?!?
Here's the latest from MAAR:
Like The Godfather: Part II, the Twin Cities housing market showed a surprisingly strong sequel to last week's huge upswing in pending sales. For the week ending September 6, there were 749 purchase agreements written—a rise of 49.8 percent from the same week in 2007. This comes on the heels of last week's then-unthinkably large increase of 51.3 percent.
There are factors at work that are exacerbating the appearance of this rebound and slightly tempering this good news. First, the sales slowdown in August and September of last year was historically extreme; current activity seems extraterrestially high, compared to 2007, but is actually only slightly above the pace of 2006. In addition, there is likely a short-term increase in sales activity as home buyers act now to take advantage of sunsetting seller-funded downpayment assistance on FHA mortgages. This program is currently the only zero-down loan option still available and is disappearing as of October 1, subject to a congressional rescue.
Other factors working to boost buyer activity include the newly authorized $7,500 federal tax credit for first-time homebuyers, home prices too good to pass on and downward pressure on interest rates.
Elsewhere in the market, the supply of homes for sale continues to shrink. There are currently 9.0 percent fewer homes on the market than there were a year ago. And we are almost dead even with the number of homes on the market at this time in 2006.
Like The Godfather: Part II, the Twin Cities housing market showed a surprisingly strong sequel to last week's huge upswing in pending sales. For the week ending September 6, there were 749 purchase agreements written—a rise of 49.8 percent from the same week in 2007. This comes on the heels of last week's then-unthinkably large increase of 51.3 percent.
There are factors at work that are exacerbating the appearance of this rebound and slightly tempering this good news. First, the sales slowdown in August and September of last year was historically extreme; current activity seems extraterrestially high, compared to 2007, but is actually only slightly above the pace of 2006. In addition, there is likely a short-term increase in sales activity as home buyers act now to take advantage of sunsetting seller-funded downpayment assistance on FHA mortgages. This program is currently the only zero-down loan option still available and is disappearing as of October 1, subject to a congressional rescue.
Other factors working to boost buyer activity include the newly authorized $7,500 federal tax credit for first-time homebuyers, home prices too good to pass on and downward pressure on interest rates.
Elsewhere in the market, the supply of homes for sale continues to shrink. There are currently 9.0 percent fewer homes on the market than there were a year ago. And we are almost dead even with the number of homes on the market at this time in 2006.
Monday, September 08, 2008
Holy Rebound, Batman!
Here's the Latest from MAAR:
Like Adam West as Batman, the market for home sales in the Twin Cities went POW! during the week ending August 30. For the week, there were 965 purchase agreements signed—a whopping increase of 51.3 percent from the same week last year. That's the highest year-over-year increase in pending sales since we began tracking that figure on a weekly basis in 2004. Home-buying activity is particularly heavy relative to last year due in all likelihood to a) the historically sluggish showing in August of last year as the credit crunch took hold, b) a bevy of buyers taking advantage of the final days of FHA's seller-funded downpayment assistance program, which sunsets on October 1 of this year and (c) new home buyers getting off the fence and taking advantage of the new home buyer tax credit of up to $7,500.
This week's edition of the MAAR Weekly Market Activity Report features updated figures for several key metrics. Days on Market Until Sale dipped slightly to 143 but remains up from last year by 5.8 percent. The Percent of Original List Price Received at Sale increased slightly to 92.7 but remains down from the healthier levels of the past several years. The Housing Affordability Index increased to 151, thanks to falling prices and interest rates.
The Months Supply of Inventory fell to 9.9 months. This means it will take the current crop of properties for sale approximately 9.9 months to completely sell through, given current sales rates. This is dead-even with this time last year, another indication that the market isn't continuing to shift in the buyer's favor anymore for the time being. A balanced market is thought to have a 5- to 6-month supply rate.
Like Adam West as Batman, the market for home sales in the Twin Cities went POW! during the week ending August 30. For the week, there were 965 purchase agreements signed—a whopping increase of 51.3 percent from the same week last year. That's the highest year-over-year increase in pending sales since we began tracking that figure on a weekly basis in 2004. Home-buying activity is particularly heavy relative to last year due in all likelihood to a) the historically sluggish showing in August of last year as the credit crunch took hold, b) a bevy of buyers taking advantage of the final days of FHA's seller-funded downpayment assistance program, which sunsets on October 1 of this year and (c) new home buyers getting off the fence and taking advantage of the new home buyer tax credit of up to $7,500.
This week's edition of the MAAR Weekly Market Activity Report features updated figures for several key metrics. Days on Market Until Sale dipped slightly to 143 but remains up from last year by 5.8 percent. The Percent of Original List Price Received at Sale increased slightly to 92.7 but remains down from the healthier levels of the past several years. The Housing Affordability Index increased to 151, thanks to falling prices and interest rates.
The Months Supply of Inventory fell to 9.9 months. This means it will take the current crop of properties for sale approximately 9.9 months to completely sell through, given current sales rates. This is dead-even with this time last year, another indication that the market isn't continuing to shift in the buyer's favor anymore for the time being. A balanced market is thought to have a 5- to 6-month supply rate.
Wednesday, September 03, 2008
Pending Sales Up 27%
Here's the latest from MAAR:
Once again, the big story in this week's activity report is the huge upswing in pending sales activity relative to one year ago. For the week ending August 23, there were 818 pending sales, an increase of 26.8 percent from the same week in 2007. Over the last three weeks, we have now posted 545 more pending sales than over the same three weeks last year.
Part of this year's increase is due to legitimate increases in demand brought about by attractive prices, still-healthy mortgage rates and a "last call" flurry of consumers utilizing FHA's seller-funded downpayment assistance program before it is discontinued on October 1. The other reason for the year-over-year surge is the Valley Fair-esque downward dive that activity took last year at this time amidst the initial media frenzy surrounding the now-infamous "credit crunch."
The supply of homes for sale continues to decrease, now down 7.7 percent from last year. For September, our Supply-Demand Ratio is 9.29, which means there are 9.29 homes for sale for each buyer in the market. This is a hearty 24.2 percent decline from last September and is due to the falling supply and rising demand.
Once again, the big story in this week's activity report is the huge upswing in pending sales activity relative to one year ago. For the week ending August 23, there were 818 pending sales, an increase of 26.8 percent from the same week in 2007. Over the last three weeks, we have now posted 545 more pending sales than over the same three weeks last year.
Part of this year's increase is due to legitimate increases in demand brought about by attractive prices, still-healthy mortgage rates and a "last call" flurry of consumers utilizing FHA's seller-funded downpayment assistance program before it is discontinued on October 1. The other reason for the year-over-year surge is the Valley Fair-esque downward dive that activity took last year at this time amidst the initial media frenzy surrounding the now-infamous "credit crunch."
The supply of homes for sale continues to decrease, now down 7.7 percent from last year. For September, our Supply-Demand Ratio is 9.29, which means there are 9.29 homes for sale for each buyer in the market. This is a hearty 24.2 percent decline from last September and is due to the falling supply and rising demand.
Monday, August 25, 2008
Legitimately Robust Current Demand
Here's the Latest from MAAR:
For the week ending August 16, 2008, there were a whopping 33.0 percent more pending sales than the same week last year—an increase of more than 200 units. This extremely strong showing is due to a combination of legitimately robust current demand and the uncharacteristically steep downward dive sales took last year after the credit markets began to constrict in August 2007. This week's figures are more in line with the equivalent (pre-credit crunch) time period in 2006—just 2.5 percent off that pace.
As for housing supply, the number of new listings on the market receded by 18.4 percent for the same time period comparison, and the total number of active properties for sale is currently 7.1 percent lower than at the same point last year.
For the week ending August 16, 2008, there were a whopping 33.0 percent more pending sales than the same week last year—an increase of more than 200 units. This extremely strong showing is due to a combination of legitimately robust current demand and the uncharacteristically steep downward dive sales took last year after the credit markets began to constrict in August 2007. This week's figures are more in line with the equivalent (pre-credit crunch) time period in 2006—just 2.5 percent off that pace.
As for housing supply, the number of new listings on the market receded by 18.4 percent for the same time period comparison, and the total number of active properties for sale is currently 7.1 percent lower than at the same point last year.
Monday, August 18, 2008
Pending sales 21% higher than one year ago!
Pop Those Corks!
Here's the latest from MAAR:
Pending sales for the week ending August 9 were a startling 21.0 percent higher than one year ago, posting 900 sales as compared to 744 a year ago. While one week of such robust increase doesn't justify the opening of stored champagne bottles, it is another welcome sign of reviving buyer demand. While a highly productive number in its own right, the year-over-year increase is somewhat amplified by just how slow August of last year was, as that is the specific month in which tightening lending standards began to take root.
New listings declined by 11.3 percent for the same time period comparison, and the total number of active properties for sale is currently 6.4 percent lower than it was one year ago. With foreclosure and short sale activity increasing, the declining supply underscores just how many traditional sellers are waiting this market out by not placing their homes up for sale.
Here's the latest from MAAR:
Pending sales for the week ending August 9 were a startling 21.0 percent higher than one year ago, posting 900 sales as compared to 744 a year ago. While one week of such robust increase doesn't justify the opening of stored champagne bottles, it is another welcome sign of reviving buyer demand. While a highly productive number in its own right, the year-over-year increase is somewhat amplified by just how slow August of last year was, as that is the specific month in which tightening lending standards began to take root.
New listings declined by 11.3 percent for the same time period comparison, and the total number of active properties for sale is currently 6.4 percent lower than it was one year ago. With foreclosure and short sale activity increasing, the declining supply underscores just how many traditional sellers are waiting this market out by not placing their homes up for sale.
Monday, August 11, 2008
Sales Tantalizing the Marketplace
For the fifth consecutive week and ninth of the last twelve, there were more purchase agreements written on homes than one year previous.
Here's the Latest from MAAR:
For the week ending August 2, there were 820 pending sales—an increase of 2.2 percent from the same week in 2007. Over the last three months, pending sales have held relatively steady, posting an increase of 0.6 percent from the same period last year. With sales tantalizing the marketplace with slight upward jiggering over the past several weeks, some might want to predict that we've reached bottom. While the news is encouraging, it's a bit premature to stake that claim. Meanwhile, housing supply is clearly in decline. New listings from the most recently reported week were a stirring 19.8 percent lower than last year and were down 12.8 percent over the last three months.
This week's edition of the MAAR Weekly Market Activity Report features updated figures for several key metrics. Days on Market Until Sale in July fell slightly to 146 but remains up 13.3 percent from July 2007. Percent of Original List Price Received at Sale decreased to 92.6 percent, also down from last year. Months Supply of Inventory is up 8.6 percent from last year at 10.5. And our Housing Affordability Index (HAI) fell 4 points from last month to 144 due to another increase in interest rates and seasonal increases in home prices. Despite the drop, the HAI remains much improved from 2006 and 2007.
Here's the Latest from MAAR:
For the week ending August 2, there were 820 pending sales—an increase of 2.2 percent from the same week in 2007. Over the last three months, pending sales have held relatively steady, posting an increase of 0.6 percent from the same period last year. With sales tantalizing the marketplace with slight upward jiggering over the past several weeks, some might want to predict that we've reached bottom. While the news is encouraging, it's a bit premature to stake that claim. Meanwhile, housing supply is clearly in decline. New listings from the most recently reported week were a stirring 19.8 percent lower than last year and were down 12.8 percent over the last three months.
This week's edition of the MAAR Weekly Market Activity Report features updated figures for several key metrics. Days on Market Until Sale in July fell slightly to 146 but remains up 13.3 percent from July 2007. Percent of Original List Price Received at Sale decreased to 92.6 percent, also down from last year. Months Supply of Inventory is up 8.6 percent from last year at 10.5. And our Housing Affordability Index (HAI) fell 4 points from last month to 144 due to another increase in interest rates and seasonal increases in home prices. Despite the drop, the HAI remains much improved from 2006 and 2007.
Monday, August 04, 2008
A New Market Picture ?
Here's the latest from MAAR:
There are fewer homes to choose from for today's prospective buyers than there were a year ago. There are currently 32,978 residential housing units up for sale in the Twin Cities region, down 5.5 percent-or about 2,000 units-from this time last year. The cause of the lessened supply is a decrease in new listings combined with more homes coming off the inventory list by way of "sold" signs. For the week ending July 26, there were only 1,816 new listings, a drop of 16.5 percent from one year ago. Newly signed purchase agreements (pending sales) for the same year-over-year comparison increased by 5.1 percent.
Less supply coupled with promising signs of demand have created a new market picture. In August, our Supply-Demand Ratio (SDR) indicates that there will be 8.68 homes for sale per buyer, a decrease of 4.2 percent from one year ago. This is the second consecutive month of downward year-over-year movement in this metric, which is a good thing. A well-balanced market for the month of August would show an SDR of about 5 homes for sale per buyer. We have a ways to go, but we're on the right track if this trend continues.
There are fewer homes to choose from for today's prospective buyers than there were a year ago. There are currently 32,978 residential housing units up for sale in the Twin Cities region, down 5.5 percent-or about 2,000 units-from this time last year. The cause of the lessened supply is a decrease in new listings combined with more homes coming off the inventory list by way of "sold" signs. For the week ending July 26, there were only 1,816 new listings, a drop of 16.5 percent from one year ago. Newly signed purchase agreements (pending sales) for the same year-over-year comparison increased by 5.1 percent.
Less supply coupled with promising signs of demand have created a new market picture. In August, our Supply-Demand Ratio (SDR) indicates that there will be 8.68 homes for sale per buyer, a decrease of 4.2 percent from one year ago. This is the second consecutive month of downward year-over-year movement in this metric, which is a good thing. A well-balanced market for the month of August would show an SDR of about 5 homes for sale per buyer. We have a ways to go, but we're on the right track if this trend continues.
Wednesday, July 30, 2008
Housing and Economic Recovery Act of 2008 PASSED!
FINALLY SOME GOOD NEWS!!!!!
H.R. 3221, the “Housing and Economic Recovery Act of 2008,” passed the House on July 23, 2008, by a vote of 272-152. On Saturday, July 26, 2008, the Senate passed the bill by a vote of 72-13. The President signed the bill on July 30, 2008. The bill includes the following provisions:
GSE Reform – including a strong independent regulator, and permanent conforming loan limits up to the greater of $417,000 or 115% local area median home price, capped at $625,500. The effective date for reforms is immediate upon enactment, but the loan limits will not go into effect until the expiration of the Economic Stimulus limits (December 31, 2008).
FHA Reform – including permanent FHA loan limits at the greater of $271,050 or 115% of local area median home price, capped at $625,500; streamlined processing for FHA condos; reforms to the HECM program, and reforms to the FHA manufactured housing program. The downpayment requirement on FHA loans will go up to 3.5% (from 3%). The effective date for reforms is immediate upon enactment, but the loan limits will not go into effect until the expiration of the Economic Stimulus limits (December 31, 2008).
Homebuyer Tax Credit - a $7500 tax credit that would be would be available for any qualified purchase between April 8, 2008 and June 30, 2009. The credit is repayable over 15 years (making it, in effect, an interest free loan).
FHA foreclosure rescue – development of a refinance program for homebuyers with problematic subprime loans. Lenders would write down qualified mortgages to 85% of the current appraised value and qualified borrowers would get a new FHA 30-year fixed mortgage at 90% of appraised value. Borrowers would have to share 50% of all future appreciation with FHA. The loan limit for this program is $550,440 nationwide. Program is effective on October 1, 2008.
Seller-funded downpayment assistance programs – codifies existing FHA proposal to prohibit the use of downpayment assistance programs funded by those who have a financial interest in the sale; does not prohibit other assistance programs provided by nonprofits funded by other sources, churches, employers, or family members. This prohibition does not go into effect until October 1, 2008.
VA loan limits – temporarily increases the VA home loan guarantee loan limits to the same level as the Economic Stimulus limits through December 31, 2008.
Risk-based pricing – puts a moratorium on FHA using risk-based pricing for one year. This provision is effective from October 1, 2008 through September 30, 2009.
GSE Stabilization – includes language proposed by the Treasury Department to authorize Treasury to make loans to and buy stock from the GSEs to make sure that Freddie Mac and Fannie Mae could not fail.
Mortgage Revenue Bond Authority – authorizes $10 billion in mortgage revenue bonds for refinancing subprime mortgages.
National Affordable Housing Trust Fund – Develops a Trust Fund funded by a percentage of profits from the GSEs. In its first years, the Trust Fund would cover costs of any defaulted loans in FHA foreclosure program. In out years, the Trust Fund would be used for the development of affordable housing.
CDBG Funding – Provides $4 billion in neighborhood revitalization funds for communities to purchase foreclosed homes.
LIHTC – Modernizes the Low Income Housing Tax Credit program to make it more efficient.
Loan Originator Requirements – Strengthens the existing state-run nationwide mortgage originator licensing and registration system (and requires a parallel HUD system for states that fail to participate). Federal bank regulators will establish a parallel registration system for FDIC-insured banks. The purpose is to prevent fraud and require minimum licensing and education requirements. The bill exempts those who only perform real estate brokerage activities and are licensed or registered by a state, unless they are compensated by a lender, mortgage broker, or other loan originator.
For more information, visit http://www.realtor.org/governmentaffairs.
H.R. 3221, the “Housing and Economic Recovery Act of 2008,” passed the House on July 23, 2008, by a vote of 272-152. On Saturday, July 26, 2008, the Senate passed the bill by a vote of 72-13. The President signed the bill on July 30, 2008. The bill includes the following provisions:
GSE Reform – including a strong independent regulator, and permanent conforming loan limits up to the greater of $417,000 or 115% local area median home price, capped at $625,500. The effective date for reforms is immediate upon enactment, but the loan limits will not go into effect until the expiration of the Economic Stimulus limits (December 31, 2008).
FHA Reform – including permanent FHA loan limits at the greater of $271,050 or 115% of local area median home price, capped at $625,500; streamlined processing for FHA condos; reforms to the HECM program, and reforms to the FHA manufactured housing program. The downpayment requirement on FHA loans will go up to 3.5% (from 3%). The effective date for reforms is immediate upon enactment, but the loan limits will not go into effect until the expiration of the Economic Stimulus limits (December 31, 2008).
Homebuyer Tax Credit - a $7500 tax credit that would be would be available for any qualified purchase between April 8, 2008 and June 30, 2009. The credit is repayable over 15 years (making it, in effect, an interest free loan).
FHA foreclosure rescue – development of a refinance program for homebuyers with problematic subprime loans. Lenders would write down qualified mortgages to 85% of the current appraised value and qualified borrowers would get a new FHA 30-year fixed mortgage at 90% of appraised value. Borrowers would have to share 50% of all future appreciation with FHA. The loan limit for this program is $550,440 nationwide. Program is effective on October 1, 2008.
Seller-funded downpayment assistance programs – codifies existing FHA proposal to prohibit the use of downpayment assistance programs funded by those who have a financial interest in the sale; does not prohibit other assistance programs provided by nonprofits funded by other sources, churches, employers, or family members. This prohibition does not go into effect until October 1, 2008.
VA loan limits – temporarily increases the VA home loan guarantee loan limits to the same level as the Economic Stimulus limits through December 31, 2008.
Risk-based pricing – puts a moratorium on FHA using risk-based pricing for one year. This provision is effective from October 1, 2008 through September 30, 2009.
GSE Stabilization – includes language proposed by the Treasury Department to authorize Treasury to make loans to and buy stock from the GSEs to make sure that Freddie Mac and Fannie Mae could not fail.
Mortgage Revenue Bond Authority – authorizes $10 billion in mortgage revenue bonds for refinancing subprime mortgages.
National Affordable Housing Trust Fund – Develops a Trust Fund funded by a percentage of profits from the GSEs. In its first years, the Trust Fund would cover costs of any defaulted loans in FHA foreclosure program. In out years, the Trust Fund would be used for the development of affordable housing.
CDBG Funding – Provides $4 billion in neighborhood revitalization funds for communities to purchase foreclosed homes.
LIHTC – Modernizes the Low Income Housing Tax Credit program to make it more efficient.
Loan Originator Requirements – Strengthens the existing state-run nationwide mortgage originator licensing and registration system (and requires a parallel HUD system for states that fail to participate). Federal bank regulators will establish a parallel registration system for FDIC-insured banks. The purpose is to prevent fraud and require minimum licensing and education requirements. The bill exempts those who only perform real estate brokerage activities and are licensed or registered by a state, unless they are compensated by a lender, mortgage broker, or other loan originator.
For more information, visit http://www.realtor.org/governmentaffairs.
Monday, July 28, 2008
Supply is Down like Grandma's Comforter
Here's the latest from MAAR:
In the Twin Cities housing market, sales are flat like a New York pizza and supply is down like grandma's comforter. Fortunately for us, the data confirms our kitschy similes. Pending sales for the week ending July 19 are ahead of the same week last year by 3.8 percent, while new listings fell by 13.0 percent for the same time period—all positive signs of a market in transition.
The total number of active listings for sale currently sits at 33,410, (comfortably) down 1,722 units—or 4.9 percent—from this time last year. Since the number of new homes coming on the market remains in decline and sales appear to have hit bottom, we can expect total inventory to remain lower than last year for some time to come.
In the Twin Cities housing market, sales are flat like a New York pizza and supply is down like grandma's comforter. Fortunately for us, the data confirms our kitschy similes. Pending sales for the week ending July 19 are ahead of the same week last year by 3.8 percent, while new listings fell by 13.0 percent for the same time period—all positive signs of a market in transition.
The total number of active listings for sale currently sits at 33,410, (comfortably) down 1,722 units—or 4.9 percent—from this time last year. Since the number of new homes coming on the market remains in decline and sales appear to have hit bottom, we can expect total inventory to remain lower than last year for some time to come.
Monday, July 21, 2008
Less is More in Local Housing Market
Here's the latest from MAAR:
Housing supply in the Twin Cities continues its descent. For the week ending July 12, there were 11.5 percent fewer new listings on the market than there were one year ago. Over the last three months, there have been roughly 4,000 fewer homes on the market than there were during the same period in 2007. The total number of properties for sale currently sits at 33,390—down 4.7 percent from this time last year.
The sales picture is slightly different, as activity has flattened after two years of downward movement. We are showing a slight 1.8 percent increase in pending sales from the same week last year. Over the last three months, there have been roughly 300 fewer pending sales—a decline of 2.7 percent.
Housing supply in the Twin Cities continues its descent. For the week ending July 12, there were 11.5 percent fewer new listings on the market than there were one year ago. Over the last three months, there have been roughly 4,000 fewer homes on the market than there were during the same period in 2007. The total number of properties for sale currently sits at 33,390—down 4.7 percent from this time last year.
The sales picture is slightly different, as activity has flattened after two years of downward movement. We are showing a slight 1.8 percent increase in pending sales from the same week last year. Over the last three months, there have been roughly 300 fewer pending sales—a decline of 2.7 percent.
Monday, July 14, 2008
Fireworks?!?!?
Here's the latest from MAAR
Prospective homeowners appear to have celebrated our Independence holiday by buying a home. For the week ending July 5, there were 735 signed purchase agreements (pending sales), up 7.3 percent from the same week one year ago. New listings increased by 2.5 percent for the same time period comparison but took the expected dive from one week prior due to the 4th of July holiday.
This week's edition of the MAAR Weekly Market Activity Report features updated figures for several important metrics:
Days on Market Until Sale fell from last month to 147 but is still 13.1 percent higher than a year ago, and the Percent of Original List Price Received at Sale increased to 92.8 percent. Both changes are additional signs that home sellers are beginning to experience some light relief.
However, not all indicators are rosy, as the Months Supply of Inventory increased slightly to 10.6 months, up 11.0 percent from last July, and the Housing Affordability Index dipped slightly to 148 due to another increase in interest rates.
For a full and detailed look at the supply and demand environment in the Twin Cities housing market, take a look at the July 2008 Housing Supply Outlook.
Prospective homeowners appear to have celebrated our Independence holiday by buying a home. For the week ending July 5, there were 735 signed purchase agreements (pending sales), up 7.3 percent from the same week one year ago. New listings increased by 2.5 percent for the same time period comparison but took the expected dive from one week prior due to the 4th of July holiday.
This week's edition of the MAAR Weekly Market Activity Report features updated figures for several important metrics:
Days on Market Until Sale fell from last month to 147 but is still 13.1 percent higher than a year ago, and the Percent of Original List Price Received at Sale increased to 92.8 percent. Both changes are additional signs that home sellers are beginning to experience some light relief.
However, not all indicators are rosy, as the Months Supply of Inventory increased slightly to 10.6 months, up 11.0 percent from last July, and the Housing Affordability Index dipped slightly to 148 due to another increase in interest rates.
For a full and detailed look at the supply and demand environment in the Twin Cities housing market, take a look at the July 2008 Housing Supply Outlook.
Monday, July 07, 2008
On the Right Track
Here's the latest from MAAR:
For the week ending June 28, pending sales in the Twin Cities housing market dipped slightly from the year previous, posting 43 fewer sales than the same week in 2007. New listings for the same time period comparison were only 6 listings higher, a meager 0.3 percent increase.
Our overall buyer trajectory this year is flat compared to a year ago. For 10 of the last 12 weeks, pending sales have been within 5 percent of 2007, either above or below. New listings, on the other hand, are showing dramatic downward movement. Over the last three months, we've posted 13.6 percent fewer listings than the same time last year.
This week's edition of the MAAR Weekly Market Activity Report features an updated Supply-Demand Ratio (SDR). The SDR for July fell slightly to 8.11, which means there are approximately 8.11 houses for each buyer in July. At 1.6 percent lower than July 2007, this is the first year-over-year decrease in SDR since MAAR began tracking the figure in 2004. Since SDR takes both supply and demand into consideration, this is the surest sign yet that the market is no longer charging headlong into the buyer's favor.
For the week ending June 28, pending sales in the Twin Cities housing market dipped slightly from the year previous, posting 43 fewer sales than the same week in 2007. New listings for the same time period comparison were only 6 listings higher, a meager 0.3 percent increase.
Our overall buyer trajectory this year is flat compared to a year ago. For 10 of the last 12 weeks, pending sales have been within 5 percent of 2007, either above or below. New listings, on the other hand, are showing dramatic downward movement. Over the last three months, we've posted 13.6 percent fewer listings than the same time last year.
This week's edition of the MAAR Weekly Market Activity Report features an updated Supply-Demand Ratio (SDR). The SDR for July fell slightly to 8.11, which means there are approximately 8.11 houses for each buyer in July. At 1.6 percent lower than July 2007, this is the first year-over-year decrease in SDR since MAAR began tracking the figure in 2004. Since SDR takes both supply and demand into consideration, this is the surest sign yet that the market is no longer charging headlong into the buyer's favor.
Monday, June 30, 2008
Market Continues to Level Out
Here's the latest from MAAR:
New listings continue to lag behind last year's pace in the Twin Cities housing market. For the week ending June 21, new listings dropped by 10.6 percent compared to the same week in 2007. This is the sixteenth consecutive week of year-over-year decline, a period during which there have been a total 5,881 fewer new listings than one year ago. The total inventory of homes currently for sale is 2.6 percent lower than last year.
On the flip side, buyer demand remains relatively flat after over two years of heavy downward momentum. Pending sales for the week ending June 21 were 1.8 percent behind the same week last year, a decline of 16 sales. This is the 9th week in the last eleven where pending sales posted figures that were within 5 percent of one year ago, either above or below.
New listings continue to lag behind last year's pace in the Twin Cities housing market. For the week ending June 21, new listings dropped by 10.6 percent compared to the same week in 2007. This is the sixteenth consecutive week of year-over-year decline, a period during which there have been a total 5,881 fewer new listings than one year ago. The total inventory of homes currently for sale is 2.6 percent lower than last year.
On the flip side, buyer demand remains relatively flat after over two years of heavy downward momentum. Pending sales for the week ending June 21 were 1.8 percent behind the same week last year, a decline of 16 sales. This is the 9th week in the last eleven where pending sales posted figures that were within 5 percent of one year ago, either above or below.
Monday, June 23, 2008
A Relatively Smooth Course
Here's the Latest from MAAR:
Home sales are continuing along a relatively smooth course so far this summer, with newly signed purchase agreements (pending sales) increasing by 3.8 percent over last year for the week ending June 14. Over the last six weeks, pending sales are behind the same time period in 2007 by only 30 sales, or 0.6 percent. When you compare that to the consistent 15–20 percent declines of the last few years, this is welcome news.
Simply matching last year's numbers does not allow home sellers to celebrate recovering buyer interest in their properties. Plus, we need to keep some perspective on what types of sales are comprising this new stabilization of activity. A hearty 27.9 percent of purchase agreements from the last six weeks were made on lender-mediated foreclosures or short sales. Buyer activity is being propped up by the increased market share of these types of properties.
Traditional sales over the same six-week period are down 21.0 percent from last year, while lender-mediated sales are up 284.5 percent from 406 sales last year to 1,561 this year. So the traditional seller still faces some challenges—and some new and very different competition.
All told, heavy buyer interest in lender-mediated properties is viewed as a positive sign. We need the prevalent lender-mediated inventory to be absorbed before our market can return to some semblance of order. The sooner these properties are worked through the market cycle, the sooner that the mist of uncertainty they bring to negotiation, appraisal and home value will lift.
Home sales are continuing along a relatively smooth course so far this summer, with newly signed purchase agreements (pending sales) increasing by 3.8 percent over last year for the week ending June 14. Over the last six weeks, pending sales are behind the same time period in 2007 by only 30 sales, or 0.6 percent. When you compare that to the consistent 15–20 percent declines of the last few years, this is welcome news.
Simply matching last year's numbers does not allow home sellers to celebrate recovering buyer interest in their properties. Plus, we need to keep some perspective on what types of sales are comprising this new stabilization of activity. A hearty 27.9 percent of purchase agreements from the last six weeks were made on lender-mediated foreclosures or short sales. Buyer activity is being propped up by the increased market share of these types of properties.
Traditional sales over the same six-week period are down 21.0 percent from last year, while lender-mediated sales are up 284.5 percent from 406 sales last year to 1,561 this year. So the traditional seller still faces some challenges—and some new and very different competition.
All told, heavy buyer interest in lender-mediated properties is viewed as a positive sign. We need the prevalent lender-mediated inventory to be absorbed before our market can return to some semblance of order. The sooner these properties are worked through the market cycle, the sooner that the mist of uncertainty they bring to negotiation, appraisal and home value will lift.
Subscribe to:
Posts (Atom)